
Income tax in Spain (IRPF): the complete 2026 guide for founders and expatriates
The IRPF — Personal income tax (IRPF) — is the progressive income tax paid by Spanish tax residents. Its general bands run from 19% to 47%, but half of the rate is set by the autonomous community: on the same income, you pay noticeably more in Barcelona than in Madrid. This guide covers the 2026 bands, the impatriate regime (Beckham law), the annual return and a line-by-line comparison with France.
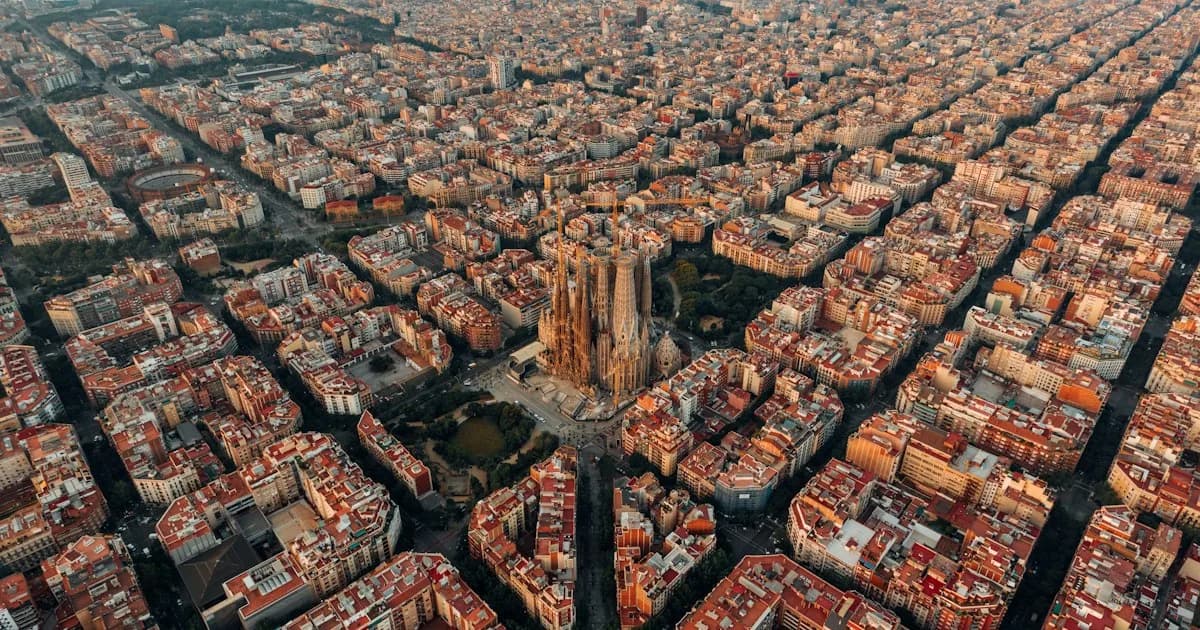
Moving to Spain — Barcelona or Madrid in particular — is a strategic opportunity for many French founders. A cost of living that is often lower than in Paris, a growing startup ecosystem and an attractive quality of life make it a destination of choice.
Spanish tax has its own particularities, though, and any founder or expatriate employee should get to grips with them before moving. Income tax in Spain (IRPF — Personal income tax (IRPF)) works under rules quite different from the French system, with significant scope for optimisation if you prepare your move properly.
This guide covers the practicalities: tax bands, the expatriate regime (Beckham law), the paperwork, and a comparison with the French system.
The 2026 IRPF bands for Spanish residents:
| Income band | IRPF rate | Regional rate (Catalonia) |
|---|---|---|
| 0 – €12,450 | 9,5% | 12% |
| 12,450 – €20,200 | 12% | 14% |
| 20,200 – €35,200 | 15% | 18,5% |
| 35,200 – €60,000 | 18,5% | 21,5% |
| 60,000 – €300,000 | 22,5% | 25,5% |
| Above €300,000 | 24,5% | 27,5% |
Source: Agencia Tributaria, 2026 bands. Total rate = state rate + autonomous community rate.
What is the IRPF?
IRPF is Spain's progressive personal income tax. It applies to Spanish tax residents: anyone who spends more than 183 days a year in Spain, or whose centre of economic interests is there.
Income subject to IRPF
- Employment income (salaries, allowances, benefits in kind)
- Investment income (dividends, interest, rental income)
- Capital gains on securities and property
- Income from economic activities (the self-employed — autónomos)
Unlike the French pay-as-you-earn system (PAS), IRPF works mainly through an annual return. Employers deduct monthly withholdings (retenciones), but the final balance is settled in the annual return.
IRPF bands for 2026
Spain applies progressive bands at national level, with each autonomous community adding its own rates on top.
State rate 2026
| Annual taxable income | State rate |
|---|---|
| Up to €12,450 | 9,5% |
| €12,450 – €20,200 | 12% |
| €20,200 – €35,200 | 15% |
| €35,200 – €60,000 | 18,5% |
| €60,000 – €300,000 | 22,5% |
| Beyond €300,000 | 23,5% |
The regional top-up: Catalonia as an example
Each autonomous community sets its own rates. In Catalonia (Barcelona), the regional top-up takes the top marginal rate to roughly 48% for income above €175,000.
Madrid, by contrast, is more favourable: its top regional rate is lower, so the same €100,000 income is taxed at roughly €4,500 more in Catalonia than in Madrid.
The CFO's view
"We see too many founders choose Barcelona for the quality of life without building tax into their model. On an income of €80,000, the tax gap between Barcelona and Madrid is more than €3,000 a year. Over 5 years, that is not trivial."
The Beckham law: the expatriate regime
Beckham Law (article 93 of the LIRPF) is the most powerful tax tool available to expatriates settling in Spain. It lets you be taxed as a non-resident for your first 6 years, at very favourable rates.
Eligibility conditions
- Not having been a Spanish tax resident in the 5 years before the move
- Moving to Spain for a job (Spanish contract) or to take up a directorship
- The work must actually be carried out in Spain
- For a company director: since the 2023 reform, there is no longer a cap on shareholding, except in an asset-holding company (25% threshold)
Tax advantages of the Beckham law
| Type of income | Tax rate |
|---|---|
| Employment income | 24% (capped at €600,000) |
| Investment income | 19% to 30%, in bands |
| Foreign income | Exempt (except for work actually performed) |
Worked example
A director on a €100,000 salary in Spain:
- Without the Beckham regime (Catalonia): tax of approximately €32,000 to €33,000
- With the Beckham law: tax €24,000 (24%)
Annual saving in this example: €8,000 to €9,000, every year for the duration of the regime (the year you change residence and the five following years). Illustrative example, before deductions and excluding capital income: the calculation must be redone for your own situation.
Limits of the Beckham law
- Duration limited to 6 years
- None of the ordinary IRPF deductions or reliefs: the flat rate applies from the first euro
- Foreign income from work actually performed abroad remains taxable in Spain
- Excludesautónomo in the ordinary sense (an employment relationship is required); since 2023, however, the digital nomad visa and ENISA certification have opened the regime to remote workers and startup founders.
Filing your IRPF return: the steps
The calendar
The filing season for the renta usually opens in April and closes at the end of June in the year after the income was earned.
Main forms
| Form | Subject | Who has to file it |
|---|---|---|
| Modelo 100 | Annual IRPF return | Any tax resident (income > €22,000) |
| Model 151 | Non-resident return under Beckham | Who can use the Beckham law |
| Modelo 030/036 | Change of tax residence | Newcomers |
| Modelo 720 | Declaring assets held abroad | Tax residents with assets > €50,000 outside Spain |
Modelo 720: a word of warning
Modelo 720 is a compulsory return for Spanish tax residents holding more than €50,000 in assets abroad (bank accounts, investments, property). Since the Court of Justice of the European Union's ruling of 27 January 2022, the fixed fines per omitted item are gone; the general tax penalty regime applies instead, but the filing obligation is still strictly enforced.
France / Spain comparison
| Criterion | France | Spain |
|---|---|---|
| Top marginal rate | 45% | 47% (state) + regional |
| Withholding at source | Yes (NOT) | Payroll withholdings + annual return |
| Expatriate regime | PEX / impatriate status | Beckham law (flat 24%) |
| Taxation of couples | Joint tax household | Individual |
| Employer social security contributions | ~40-45% | ~30-32% |
| Declaring foreign assets | Yes (form 3916) | Modelo 720 (informational return, monitored) |
Worked example: an employee on €60,000 gross
| Post | France (mainland) | Spain (Barcelona, without Beckham) | Spain (with Beckham) |
|---|---|---|---|
| Income tax | ~€11,500 | ~€10,200 | ~€14,400 (1) |
| Employee contributions | ~€12,600 | ~€9,800 | ~€9,800 |
| Employer contributions | ~€24,000 | ~€18,000 | ~€18,000 |
| Total employer cost | ~€96,000 | ~€87,800 | ~€92,200 |
(1) The Beckham law applies a flat 24% with no allowances, so the tax is slightly higher at this level. The Beckham advantage really kicks in above €70,000.
The CFO's view
"The France-Spain comparison is not just about the tax rate. Employer social security contributions are 8 to 12 points lower in Spain. For an employee on €50,000 gross, the total employer saving is more than €8,000 a year. That is the figure to look at, not just IRPF."
Income tax for business owners
Director of an SL (Sociedad Limitada)
The pay of a director of a Spanish SL is subject to IRPF under the ordinary rules. This is where the Beckham law pays off most: a director earning €80,000 pays 24% tax (€19,200) against 32% to 35% without Beckham.
The IS (Impuesto de Sociedades) applies to the company itself, at a standard rate of 25%.
Self-employed (autónomo)
The regime for autónomos is separate and does not qualify for the Beckham law. Income is taxed under the progressive IRPF bands. Compulsory social security contributions start at around €230 a month (since the 2023 reform).
Common mistakes to avoid
Mistake 1 — Failing to declare French income. Even under the Beckham law, certain non-exempt income must be declared. The Spanish tax authority exchanges information with France.
Mistake 2 — Confusing administrative residence with tax residence. You become a Spanish tax resident after 183 days in the country. The 183-day test is strict.
Mistake 3 — Forgetting Modelo 720. An N26 or Revolut account, a French assurance-vie or a flat in Paris all count as foreign assets in Spanish eyes. The fixed fines were scrapped after the 2022 CJEU ruling, but the return is still compulsory and still checked.
Mistake 4 — Underestimating processing times. Obtaining the NIE (Número de Identidad de Extranjero), opening a bank account and registering with the tax authorities: allow 4 to 8 weeks in total.
Frequently asked questions about income tax in Spain
What are the IRPF bands in Spain for 2026?
The general state bands run from 19% (up to €12,450) to 47% (above €300,000). In between: 24% from €12,450 to €20,200, 30% from €20,200 to €35,200, 37% from €35,200 to €60,000 and 45% from €60,000 to €300,000. Your final rate also depends on the regional share set by the autonomous community where you live.
How does the regional part of IRPF work?
Each autonomous community (Catalonia, Madrid, Andalusia, the Valencian Community and so on) applies its own bands and deductions on top of the state share. Madrid's regional rates are below the national average, while Catalonia and the Valencian Community apply higher marginal rates (which can exceed 50%).
How is savings income taxed in Spain?
Investment income (dividends, capital gains) is taxed under separate bands, from 19% (up to €6,000) to 28% (above €300,000). It does not follow the progressive IRPF bands for employment income.
Does the Beckham law apply to freelancers?
Not as an ordinary autónomo: the regime requires an employment relationship. Since 2023, two routes have opened up for the self-employed: the digital nomad visa (as an employee of a foreign company) and ENISA certification for startup founders.
How long does it take to become a Spanish tax resident?
As soon as you spend more than 183 days in Spain in a calendar year, consecutive or not — or as soon as your centre of economic interests or your family home is there. Any one criterion is enough.
Do I have to declare my French income in Spain?
Yes, if you are a Spanish tax resident. The France-Spain tax treaty prevents double taxation, but you still have to declare it.
What is the total employer cost of a €50,000 employee in Spain?
Around €65,000 (salary plus employer contributions of ~30%). → Discover our Fractional CFO services in Barcelona
Moving to Spain — or setting up a team there?
Tax bands, autonomous community, Beckham law, employer cost: a 30-minute diagnostic is enough to put figures on your situation and lock in the timetable.
Request a diagnosticDiscover our Fractional CFOs in Barcelona.
Sources and references
- Impuesto sobre la Renta de las Personas Físicas (IRPF) — bands and obligations — Agencia Tributaria (AEAT).
- Ley 35/2006 del Impuesto sobre la Renta de las Personas Físicas, consolidated text — Boletín Oficial del Estado (BOE).
Let's talk about your project
Tell us your priority, situation and timeline. The first conversation helps define the scope and next steps.